Insurance rarely looks like a traditional business: money comes in today, while the financial consequences of a claim may arrive years later. That unusual timing creates a powerful business model built around risk, capital, pricing, and disciplined financial management.
Insurance companies earn revenue primarily by collecting premiums, but their profitability can also come from investing premium funds, underwriting risks effectively, charging permitted fees, managing reinsurance, and expanding through distribution partnerships. Understanding how insurance companies make money helps explain how these businesses balance premium income, investment returns, and claims expenses.
However, revenue growth alone does not guarantee success. Rising claims, weak pricing, fraud, investment losses, and operating costs can quickly erode margins. For entrepreneurs, investors, and business-minded readers, understanding how insurers make money reveals the economics behind one of the world’s most important financial industries.
This blog explores ten major revenue-generating methods shaping insurance businesses in 2026.
How Insurance Works?
Insurance is a financial risk-transfer mechanism: customers pay premiums to an insurer for protection against specified losses. Instead of bearing the full cost of an uncertain event alone, policyholders pool risks with many others. The insurer uses statistical data, policy terms, and pricing models to estimate claims and determine premiums.
For insurers, the business is managing the gap between money collected and money paid out. Premiums provide cash flow, while claims may arise later. This timing allows insurers to invest funds, creating another revenue source. However, profitable insurance requires underwriting because pricing risk too cheaply can turn sales into losses.
Business performance depends on more than premium growth. Insurers must control claims, expenses, fraud, investment risk, and capital requirements. A company can expand yet weaken if its policies generate excessive claims. The commercial challenge is clear: price uncertainty accurately, manage capital efficiently, and remain strong enough to honour future obligations.
Main Ways Insurance Companies Make Money
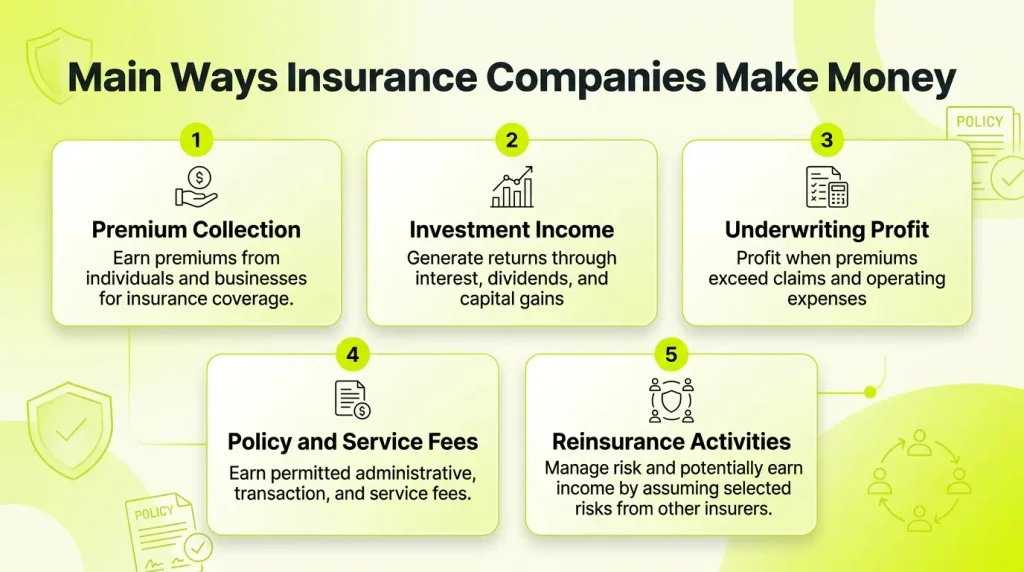
Insurance companies operate a multi-stream revenue model rather than relying solely on premiums. Their profitability depends on balancing underwriting performance, investment income, fees, expenses, and disciplined management of policyholder risks.
- Premium Collection: Insurers collect premiums from individuals and businesses in exchange for coverage. Pricing these premiums accurately allows companies to generate sufficient revenue while accounting for expected claims and operating costs.
- Investment Income: Insurers invest premium funds before claims become payable. Interest, dividends, and capital gains from these investments can create substantial income, particularly when companies maintain large pools of investable assets.
- Underwriting Profit: Underwriting profit occurs when premiums collected exceed claims and operating expenses. Strong risk assessment, accurate pricing, efficient claims management, and disciplined policy selection are essential for achieving sustainable underwriting profitability.
- Policy and Service Fees: Some insurers generate additional revenue through administrative charges, policy fees, transaction fees, service charges, and other permitted expenses. These supplementary streams can strengthen revenue without directly increasing insurance premiums.
- Reinsurance Activities: Some insurers transfer portions of their risks to other insurers through reinsurance. Depending on their business model, insurers can earn income by assuming selected risks while carefully managing potential claims exposure.
10 Ways How Insurance Companies Make Money in 2026
1. Collecting Insurance Premiums
Best For: Insurers seeking predictable recurring revenue by pricing customer risk accurately across different insurance products and market segments.
Premiums are the foundation of the insurance business. Customers pay insurers regularly or upfront to receive financial protection against specified risks, creating the primary revenue pool. Insurers estimate expected claims, administrative expenses, inflation, and risk exposure before setting premiums.
Profit depends on maintaining an adequate margin between premium income and eventual costs. However, aggressive pricing can attract customers quickly while creating future losses if claims exceed expectations, making actuarial discipline commercially essential.
How It Generates Revenue:
- Charges customers recurring policy premiums
- Prices premiums according to risk
- Adjusts premiums during policy renewals
- Offers higher-priced specialised coverage
- Expands premium collections through customer acquisition
2. Investment Income
Best For: Insurance companies with substantial investable funds seeking additional income from premiums held before future claims become payable.
Insurance companies often receive premiums before they need to pay claims, creating investable funds commonly associated with the industry’s “float.” Insurers invest these assets across permitted instruments to generate interest, dividends, and other investment returns.
Investment income can materially support profitability, particularly when underwriting margins are narrow. The strategy requires careful asset-liability management because insurers must balance return objectives with liquidity, regulatory requirements, credit risk, and the timing of future claims.
How It Generates Revenue:
- Earns interest from fixed-income investments
- Receives dividends from equity holdings
- Generates returns from permitted securities
- Reinvests investment income for compounding
- Matches investments against expected liabilities
3. Underwriting Profit
Best For: Insurers focused on disciplined risk selection, accurate pricing, and controlling claims and operating expenses below premium collections.
Underwriting profit occurs when an insurer’s earned premiums exceed claims and underwriting-related expenses. It represents the financial outcome of accurately assessing and pricing risk rather than relying on investment returns to compensate for weak insurance operations.
Strong underwriting requires extensive data, actuarial modelling, risk segmentation, and claims discipline. Conversely, underpricing policies may boost short-term sales but produce substantial future losses. Sustainable insurers therefore treat underwriting quality as a core commercial advantage.
How It Generates Revenue:
- Prices policies above expected costs
- Selects risks with favourable profiles
- Controls claims through effective assessment
- Reduces unnecessary underwriting expenses
- Adjusts pricing using claims experience
4. Reinsurance
Best For: Insurers and specialist reinsurers managing large risks while generating revenue through structured risk-sharing arrangements across insurance markets.
Reinsurance involves transferring part of an insurer’s risk exposure to another insurance company, known as a reinsurer. Reinsurers receive premiums for assuming portions of potential claims, creating a significant business model of their own.
Primary insurers use reinsurance to manage catastrophic losses, expand underwriting capacity, and protect capital. Reinsurers, meanwhile, diversify risks across geographies and industries. Profitability depends heavily on pricing catastrophe exposure, modelling losses, and maintaining sufficient reserves.
How It Generates Revenue:
- Collects premiums from primary insurers
- Prices transferred risks using models
- Diversifies exposure across multiple markets
- Earns fees through specialised arrangements
- Manages catastrophe risks for insurers
5. Policy Fees and Charges
Best For: Insurers seeking supplementary revenue from administrative services, policy transactions, changes, and other permitted customer-facing activities.
Premiums are not always the only customer payment associated with insurance. Depending on the product and applicable regulations, insurers may charge administrative, policy, transaction, service, or other permitted fees. These charges can create additional revenue while helping recover the costs of processing and servicing policies.
Their commercial importance varies considerably across insurance categories. However, excessive fees can increase customer dissatisfaction and affect retention, meaning insurers must balance revenue generation with transparent pricing and competitiveness.
How It Generates Revenue:
- Charges permitted policy administration fees
- Collects transaction-related service charges
- Recovers certain processing expenses
- Charges fees for policy changes
- Monetises specialised administrative services
6. Claims Management and Cost Control
Best For: Insurers improving margins by reducing avoidable claims costs, operational inefficiencies, fraud, leakage, and unnecessary administrative expenditure.
Insurance companies can protect profitability by controlling how much they ultimately spend on claims and operations. Advanced claims systems, fraud detection, automation, analytics, and efficient settlement processes can reduce unnecessary expenses without undermining legitimate customer payments.
The objective is not simply to minimise claims but to pay valid claims accurately while preventing waste and abuse. Better cost control can improve underwriting results, particularly when premium growth is constrained or competition limits pricing flexibility.
How It Generates Revenue:
- Reduces fraudulent claim payments
- Detects suspicious claims using analytics
- Automates repetitive claims processes
- Limits unnecessary administrative expenses
- Improves settlement accuracy and efficiency
7. Bancassurance and Distribution Partnerships
Best For: Insurers expanding customer reach through banks, financial institutions, agents, brokers, digital platforms, and strategic distribution networks.
Insurance companies can increase revenue by distributing policies through established financial and commercial networks. Bancassurance, agency relationships, brokers, and digital partnerships provide access to customers without requiring insurers to build every distribution channel independently.
These arrangements can accelerate policy sales, improve cross-selling, and reduce customer acquisition friction. However, commissions and partnership costs reduce margins, while dependence on external distributors can create strategic and regulatory risks that insurers must manage carefully.
How It Generates Revenue:
- Expands policy sales through banks
- Reaches customers through insurance agents
- Uses brokers for specialised distribution
- Cross-sells insurance alongside financial products
- Reduces direct customer acquisition barriers
8. Selling Investment-Linked Insurance Products
Best For: Insurers combining protection and investment features to attract customers seeking insurance coverage alongside long-term wealth-building opportunities.
Investment-linked insurance products combine insurance protection with an investment component, allowing insurers to earn revenue through premiums and associated product charges. Depending on the structure, customers’ funds may be allocated across investment options while insurance coverage remains active.
Insurers can generate fees through administration, fund management, policy servicing, and other permitted charges. These products can broaden revenue opportunities, although performance, market volatility, transparency, and regulatory requirements significantly influence customer demand and profitability.
How It Generates Revenue:
- Collects premiums from policyholders
- Charges permitted policy administration fees
- Earns investment management-related charges
- Generates fund servicing revenue
- Retains insurance-related premium components
9. Selling Additional and Cross-Sold Coverage
Best For: Insurers increasing customer value by selling complementary policies, coverage upgrades, riders, and additional protection to existing policyholders.
Existing customers represent an important revenue opportunity because insurers already possess relationship history, policy information, and distribution access. Companies can cross-sell complementary products such as riders, additional coverage, or different insurance policies based on customer needs.
Increasing products per customer can raise premium income while potentially reducing acquisition costs compared with finding entirely new customers. The strategy works best when recommendations genuinely match customer requirements; poorly targeted cross-selling can increase cancellations and weaken long-term trust.
How It Generates Revenue:
- Adds optional riders to policies
- Upgrades customers into broader coverage
- Cross-sells multiple insurance products
- Increases premiums per existing customer
- Reduces acquisition costs through cross-selling
10. Asset and Risk Management Services
Best For: Large insurers and insurance groups monetising investment expertise, institutional capabilities, and specialised financial services beyond traditional underwriting.
Some insurance groups extend their business beyond traditional risk protection by managing assets or providing specialised financial services. Where permitted by their structure and regulations, insurers can earn management fees from investment portfolios, institutional mandates, or related services.
These activities diversify revenue and can leverage capabilities already developed for managing policyholder funds. However, expansion introduces additional market, operational, compliance, and reputational risks, requiring strong governance and clear separation between insurance obligations and investment activities.
How It Generates Revenue:
- Charges investment management fees
- Manages institutional investment mandates
- Provides specialised financial services
- Earns fees from asset administration
- Diversifies revenue beyond insurance underwriting
Suggested Read
Life Insurance vs Health Insurance vs General Insurance: Revenue Differences
The three insurance categories generate revenue differently, and understanding how insurance companies make money requires examining their risk duration, claim patterns, pricing structures, and investment opportunities. For businesses, margins depend on managing these differences effectively.
| Insurance Type | Main Revenue Source | Key Profit Driver | Major Risk |
| Life Insurance | Premiums + investments | Long-term investment returns | Mortality and longevity risk |
| Health Insurance | Premiums | Claims and medical-cost control | Rising healthcare costs |
| General Insurance | Premiums + investment income | Underwriting discipline | Frequent or severe claims |
Key Factors That Affect Insurance Profitability
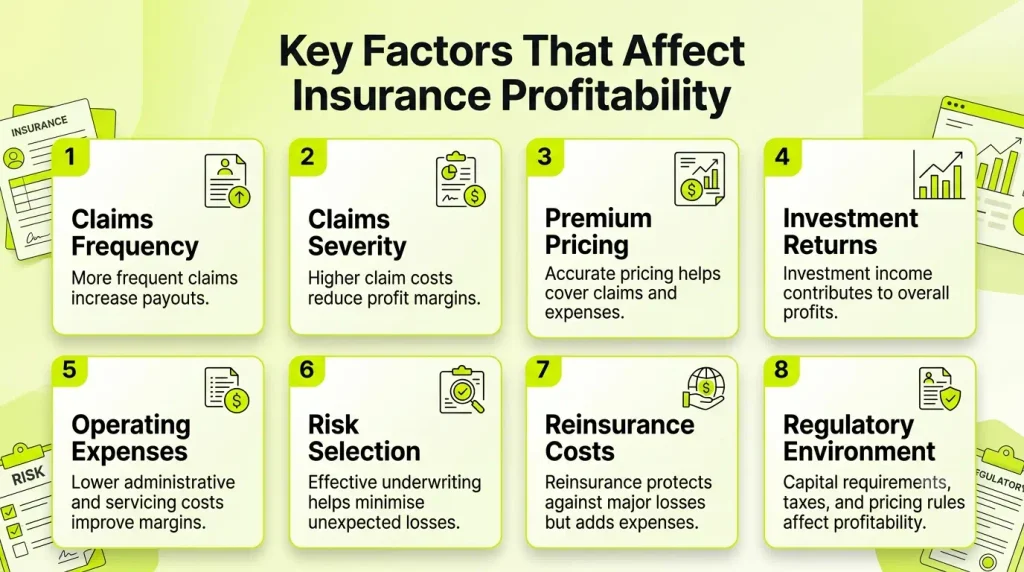
Insurance profitability depends on how effectively insurers balance premium income, claims, investment returns, operating expenses, and risk exposure while maintaining sustainable pricing and customer trust.
- Claims Frequency: Frequent claims increase payouts, reducing underwriting margins and requiring insurers to price policies according to expected loss patterns.
- Claims Severity: Higher claim values can significantly increase expenses, particularly when medical costs, repair prices, or catastrophic losses rise unexpectedly.
- Premium Pricing: Accurate risk-based pricing helps insurers collect sufficient premiums to cover claims, operating expenses, reserves, and desired profit margins.
- Investment Returns: Insurers invest collected premiums before claims are paid, making investment income an important contributor to overall profitability.
- Operating Expenses: Lower administrative, distribution, technology, and servicing costs can improve margins without necessarily requiring higher premiums from policyholders.
- Risk Selection: Careful underwriting helps insurers identify and price high-risk customers appropriately, reducing unexpected losses and improving portfolio quality.
- Reinsurance Costs: Reinsurance protects insurers from severe losses, but excessive premiums or unfavorable terms can reduce the profitability of insurance portfolios.
- Regulatory Environment: Capital requirements, pricing restrictions, consumer protections, taxes, and reporting obligations can directly influence insurers’ costs, flexibility, and profitability.
Conclusion
Insurance is ultimately a business of pricing uncertainty, managing capital, and controlling costs, not simply collecting premiums. Understanding how insurance companies make money involves looking at their revenue streams, including premiums, investment income, underwriting, reinsurance, policy fees, distribution partnerships, cross-selling, and specialised financial services.
In 2026, however, multiple revenue streams do not automatically translate into profitability. Claims frequency, loss severity, pricing accuracy, investment performance, operating efficiency, regulation, and reinsurance costs can quickly reshape margins.
For business-minded investors and entrepreneurs, the key lesson is to examine the quality and sustainability of revenue rather than headline premium growth alone. An insurer that expands rapidly without disciplined underwriting may create significant future liabilities.
Long-term performance therefore depends on balancing growth with risk selection, capital efficiency, customer retention, technological capabilities, and the ability to honour obligations profitably.
FAQs
How do Insurance Companies Make Money?
Primarily through premiums, investment income, underwriting profits, policy fees, and other permitted financial services.
What is the Biggest Source of Insurance Revenue?
Premium collection is generally the core revenue source, although investment income can significantly influence overall profitability.
Can Insurers be Profitable Without Underwriting Profits?
Yes. Investment income can support earnings, but consistently weak underwriting can create substantial long-term financial risks.
Why is Investment Income Important for Insurers?
Insurers can invest premiums before claims become payable, generating interest, dividends, and other investment returns.
What Reduces Insurance Profitability?
High claim frequency, severe losses, inaccurate pricing, fraud, rising expenses, poor investments, and expensive reinsurance can reduce margins.
How Can Insurers Improve Profitability in 2026?
They can strengthen risk pricing, automate operations, control claims costs, diversify revenue, improve customer retention, and manage investments prudently.