Churches need financial resources to operate their ministries, maintain buildings, support staff, organise community programs, and fund charitable activities. Unlike conventional businesses, churches generally rely on donations and contributions from members and supporters rather than selling products for profit.
Offerings, tithes, fundraising events, grants, and donations provide important sources of income. Some churches may also generate revenue through bookshops, event spaces, educational programs, investments, or property rentals. The exact sources of church income can vary depending on size, denomination, location, activities, and financial structure.
Understanding how do churches make money provides insight into how religious organisations fund their operations and community work.
Do Churches Pay Taxes?
In the United States, qualifying churches are generally exempt from federal income tax under Section 501(c)(3), and churches that meet the requirements do not have to apply separately for IRS recognition of their tax-exempt status. However, tax exemption does not mean that every type of church income is automatically tax-free.
A church may owe tax on income from an unrelated business activity that is regularly conducted and not substantially connected to its religious purpose. For example, certain commercial activities may create unrelated business taxable income. If a qualifying organisation has $1,000 or more in gross income from an unrelated business, it generally must file Form 990-T.
Churches may also have other tax and employment-related obligations depending on their activities and circumstances. Therefore, whether a church pays taxes depends on the type of income, activity, and applicable federal, state, and local rules.
How Do Churches Make Money? 10 Key Income Sources
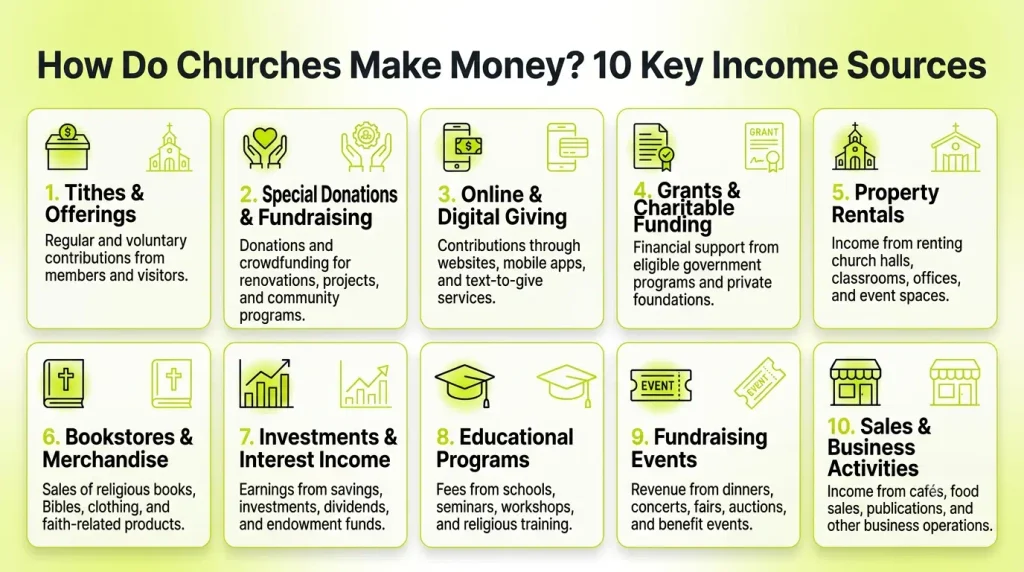
Churches use different sources of income to fund worship services, staff, building maintenance, community programs, charitable activities, and other ministry expenses. Common sources include member contributions, fundraising, grants, property income, and various church-related activities.
1. Tithes & Offerings
Tithes and offerings are traditional sources of church income. Members and visitors may contribute regularly or make additional donations during services, helping churches meet ongoing operating expenses.
- Tithes: Traditionally, a tithe refers to giving one-tenth of income to support religious work, although practices and expectations vary among churches.
- Offerings: Members may provide additional voluntary contributions beyond regular giving, often through collection plates, envelopes, online payments, or digital giving systems.
2. Special Donations & Fundraising
Churches may organise special fundraising campaigns when they need substantial funds for specific projects, repairs, community programs, or major purchases.
- Capital Campaigns: A church may ask members and supporters to make larger commitments over a defined period to finance construction, renovation, or expansion projects.
- Crowdfunding: Churches can use online fundraising platforms or their own digital systems to collect contributions for urgent repairs, community projects, or families requiring assistance.
3. Online & Digital Giving
Digital payment methods have made it easier for churches to receive contributions from members who attend services physically or participate remotely.
- Online Donations: Churches may accept contributions through their websites, mobile applications, payment portals, or other digital platforms.
- Text-to-Give: Some churches provide dedicated text numbers that allow supporters to make donations using their mobile phones.
4. Grants & Charitable Funding
Some churches and religious organisations receive grants to support community programs, education, food assistance, disaster relief, or other charitable activities.
- Government Grants: Depending on applicable rules, religious organisations may qualify for certain grants supporting eligible community services.
- Foundation Grants: Private foundations and charitable organisations may provide funding for specific projects or community initiatives.
5. Property Rentals
Churches with unused rooms, halls, classrooms, parking areas, or other facilities may generate income by allowing outside groups to use their property.
- Event Spaces: Church halls can sometimes be rented for meetings, weddings, conferences, classes, or community events.
- Facility Rentals: Organisations may also rent classrooms, offices, kitchens, or other suitable spaces when available.
6. Church Bookstores & Merchandise
Some churches operate bookstores or sell religious merchandise to members and visitors. These activities can provide additional funds while supporting the organisation’s ministry.
- Books & Study Materials: Churches may sell Bibles, religious books, devotionals, study guides, and educational materials.
- Merchandise: Items such as clothing, artwork, music, accessories, and other faith-related products may also generate revenue.
7. Investments & Interest Income
Larger churches or religious organisations may hold savings, investments, or other financial assets that generate interest, dividends, or other investment income.
- Investment Accounts: Organisations may invest funds according to their financial policies and applicable legal requirements.
- Endowment Funds: Some churches maintain endowments whose investment returns can provide long-term financial support for ministry or charitable activities.
8. Educational Programs
Churches may operate educational activities such as schools, seminars, conferences, workshops, or religious training programs that can involve fees or tuition.
- Classes & Workshops: Participants may pay fees for certain educational programs, skills-based activities, or specialised workshops.
- Schools & Training: Some religious organisations operate schools, seminaries, or training institutions that receive tuition or program-related payments.
9. Fundraising Events
Churches may organise community events to raise money for specific programs or general operating needs. These events can also encourage participation beyond regular services.
- Community Events: Activities may include dinners, concerts, fairs, auctions, or other gatherings where proceeds support church programs.
- Benefit Events: Some events are organised specifically to raise funds for missions, charitable projects, building improvements, or families in need.
10. Sales & Related Business Activities
Some churches may generate additional revenue through activities involving merchandise, services, or other business operations. The tax treatment of these activities depends on the circumstances and applicable laws.
- Cafés or Food Sales: Certain churches may operate cafés, coffee shops, or food programs that generate receipts.
- Other Activities: Churches may also receive income from publications, licensing, or other activities. In the United States, unrelated business activities can have separate tax rules, although various exceptions and exclusions apply.
Suggested Read:
Tithing Explained: How Much Do Members Typically Give?
Tithing is a traditional Christian practice in which a person gives a portion of their income to their church or congregation. The word “tithe” traditionally means one-tenth, so a 10% contribution is commonly associated with the practice. Understanding how do churches make money also involves looking at tithing, as these contributions can help support church operations and religious activities.
However, not every Christian denomination or church requires members to give exactly 10%. Giving practices can differ based on religious teachings, personal beliefs, financial circumstances, and church traditions.
Pew Research has found substantial variation in tithing across Christian groups and countries. For example, a 2011 Pew survey found that 79% of U.S. Mormons reported paying a full 10% tithe, while surveys in other Christian populations have found much lower participation.
Common approaches to tithing include:
- 10% of income: The traditional definition of tithing is giving one-tenth of income to the church or congregation.
- Regular contributions: Some members contribute weekly or monthly rather than calculating a formal 10% tithe.
- Voluntary giving: Many churches emphasize giving according to individual willingness and financial circumstances rather than requiring a fixed percentage.
- Additional offerings: Members who tithe may also make separate donations for missions, charity, building projects, or special church programs.
- Different denominational practices: Expectations surrounding tithing vary considerably among Christian traditions. Pew research has documented significant differences in reported tithing across countries and denominations.
For example, someone earning $4,000 per month who follows a 10% tithing practice would contribute $400 per month. However, this is an illustration of the traditional calculation, not a universal requirement for church members.
How Churches Use Their Income
Churches use their income to support religious services, employees, buildings, community programs, charitable activities, education, outreach, and other expenses required for daily operations.
- Worship Services: Churches pay for music, equipment, supplies, technology, decorations, utilities, and other expenses required to conduct regular worship services.
- Staff Salaries: Income helps pay pastors, administrative employees, musicians, teachers, maintenance workers, and other staff members supporting church operations.
- Building Maintenance: Churches spend money on repairs, cleaning, insurance, utilities, renovations, security, landscaping, and ongoing property maintenance costs.
- Community Outreach: Funds support food drives, clothing programs, counseling services, community events, educational activities, and assistance for people experiencing financial hardship.
- Charitable Giving: Churches may allocate money toward local charities, humanitarian organisations, missions, disaster relief efforts, and other charitable initiatives.
- Youth Programs: Income can fund youth groups, educational materials, activities, camps, transportation, sports programs, and supervised community events.
- Missionary Work: Some churches provide financial support for missionaries, international projects, evangelism programs, travel expenses, and overseas community development initiatives.
- Technology and Administration: Churches pay for websites, software, accounting services, livestreaming equipment, communication systems, office supplies, and administrative expenses.
- Education: Funds may support Sunday schools, Bible studies, seminars, training programs, libraries, educational materials, and other religious learning activities.
- Future Reserves: Some churches maintain financial reserves or savings to prepare for unexpected expenses, major repairs, emergencies, and future ministry projects.
Large Churches vs Small Churches: Income Differences
Church income can differ considerably based on congregation size, location, property, programs, donations, and organizational structure. Large churches generally have more potential revenue sources, while small churches often operate with smaller and more limited budgets.
| Factor | Large Churches | Small Churches |
| Congregation Size | Usually serve larger numbers of members and attendees, creating a broader potential donor base. | Usually have fewer members, resulting in a smaller pool of regular contributors. |
| Donations & Tithes | May receive substantial contributions because of their larger membership and wider supporter networks. | Often depend heavily on regular giving from a relatively small congregation. |
| Fundraising | Can organize large campaigns, conferences, events, and capital drives with broader participation. | May rely on smaller community fundraising events and member contributions. |
| Property Income | May own multiple buildings, halls, offices, or other properties that can potentially generate rental income. | Usually have fewer properties and therefore fewer opportunities for rental revenue. |
| Programs | May operate schools, bookstores, cafés, media programs, or conferences that create additional income sources. | Typically operate fewer commercial or educational activities because of limited resources. |
| Staff & Expenses | Have larger budgets but also face higher costs for salaries, facilities, technology, programs, and administration. | Have smaller operating expenses but may have fewer paid employees and programs. |
| Financial Reserves | Larger organizations may have greater capacity to maintain reserves, endowments, or investments. | Smaller churches may have limited reserves and depend more directly on current income. |
| Income Stability | Multiple revenue sources can provide greater diversification, although income can still fluctuate. | Income may be more dependent on regular member giving and local economic conditions. |
Overall, church size does not automatically determine financial strength. A large church may generate more revenue but also have substantially higher expenses, while a small church may operate successfully with a smaller budget and fewer financial commitments.
Are Church Finances Public? Transparency & Accountability
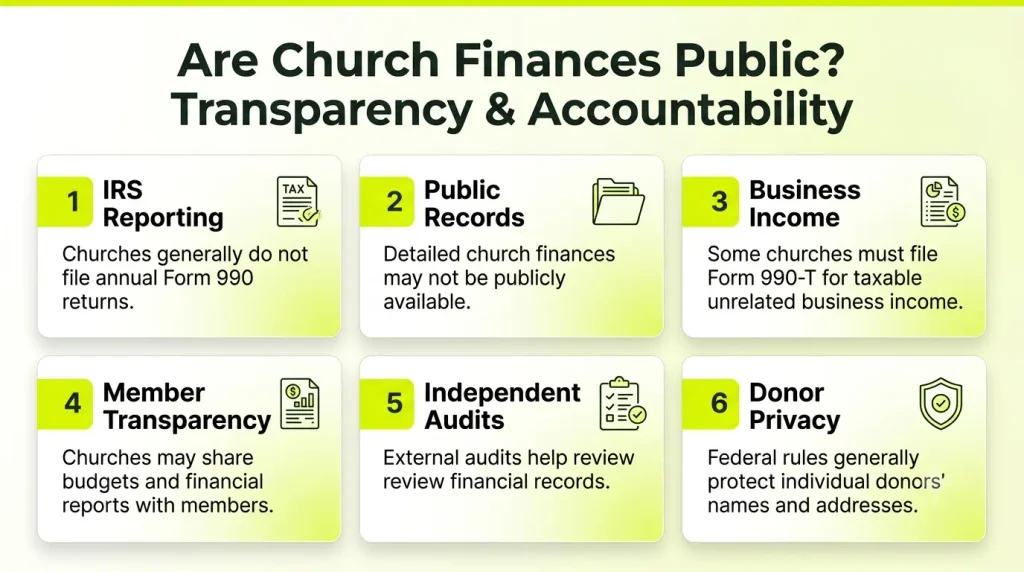
Church financial transparency depends on the country, legal structure, denomination, and type of organisation. Understanding how do churches make money also involves examining how they manage and disclose their finances.
In the United States, churches are generally exempt from the requirement to file an annual Form 990 with the IRS, meaning their complete financial information is not automatically available to the public through that filing. However, churches may voluntarily provide financial reports to members, publish budgets, disclose major expenses, or undergo independent audits as part of their internal accountability practices.
- IRS Reporting: Churches generally do not have to file annual Form 990 returns, unlike many other tax-exempt organizations.
- Public Financial Records: Because churches are generally exempt from annual Form 990 filing, detailed financial information may not be publicly available through the IRS.
- Unrelated Business Income: A church that has taxable unrelated business income may have to file Form 990-T, which is subject to public-inspection requirements.
- Member Transparency: Churches may voluntarily share annual financial statements, budgets, spending reports, or information about major projects with their congregations.
- Independent Audits: Some churches choose to use external accountants or auditors to review their financial records, although requirements vary according to the organisation and applicable rules.
- Donor Information: For organisations subject to public-disclosure requirements, federal rules generally protect the names and addresses of individual contributors from public disclosure.
Overall, tax exemption and financial transparency are separate issues. A church may have legal tax-exempt status without being required to publicly disclose the same level of financial information as organisations that file Form 990.
Legal & Tax Considerations Around Church Income
Churches can receive income from donations, tithes, fundraising, property, investments, and other activities, but tax treatment depends on the organisation’s legal status and the nature of its income. In the United States, qualifying churches generally receive federal tax-exempt treatment under Section 501(c)(3). However, tax exemption does not automatically apply to every income-producing activity.
- Tax-Exempt Status: Qualifying churches generally do not pay federal income tax on income related to their exempt religious purposes. Churches that meet Section 501(c)(3) requirements are generally automatically considered tax-exempt.
- Unrelated Business Income: Income from a regularly conducted trade or business that is not substantially related to the church’s exempt purpose may be subject to unrelated business income tax.
- Form 990-T: A tax-exempt organisation generally must file Form 990-T when it has $1,000 or more of gross income from an unrelated business.
- Donations: Contributions to qualifying churches can generally be eligible for charitable deductions for donors, subject to applicable tax rules.
- Employment Taxes: Churches with employees can have federal employment-tax responsibilities, including withholding income taxes and handling Social Security and Medicare requirements. Special rules may apply to churches and clergy.
- Record Keeping: Churches should maintain accurate records of donations, expenses, payroll, investments, fundraising activities, and other financial transactions to support proper compliance.
- State and Local Rules: Federal tax exemption does not eliminate every state or local requirement. Churches may have additional obligations depending on their location and activities.
- Private Benefit Restrictions: A Section 501(c)(3) organisation cannot allow its net earnings to improperly benefit private individuals.
Conclusion
Churches generate income through various sources, including tithes, offerings, online donations, fundraising events, grants, investments, and property rentals. Understanding how do churches make money helps explain how these financial resources cover staff salaries, building maintenance, worship services, community outreach, educational programs, and charitable activities. While donations remain the primary source of income for many churches, larger organisations may have additional revenue streams to support their operations.
The amount of money a church receives depends on its congregation, location, activities, and financial management. Transparent accounting and responsible spending help churches maintain donor trust, manage expenses, and continue serving their communities while fulfilling their religious and charitable missions.
FAQs
How do Churches Make Money?
Churches commonly receive money through tithes, offerings, donations, fundraising events, grants, and other contributions from members and supporters.
Do Churches Make Money from Donations?
Yes. Donations and regular contributions are major sources of income for many churches and can help fund operating expenses, staff, programs, and charitable activities.
Can Churches Earn Money from Businesses?
Some churches may generate additional income through bookstores, event spaces, educational programs, property rentals, investments, or other permitted activities.
What do Churches Spend their Money on?
Church funds may support salaries, building maintenance, utilities, worship services, community programs, missions, charitable activities, education, and administrative expenses.
Are Churches Required to Pay Taxes on their Income?
Tax treatment depends on the country and the nature of the income. In the United States, qualifying churches generally receive federal tax-exempt status, although certain income-generating activities may have different tax rules.